Global Inference Semiconductors & Edge Accelerator Chips Market — Intelligence Report
Demand outlook, competitive shifts, and capacity economics across cloud, enterprise, automotive, industrial, and device-edge deployments, 2025–2032
Nexvora Intelligence market report on Global AI Inference Semiconductors & Edge Accelerator Chips Market — Intelligence Report.
per extra user
Instant access after payment. Secure via Razorpay.
The opening view — free.
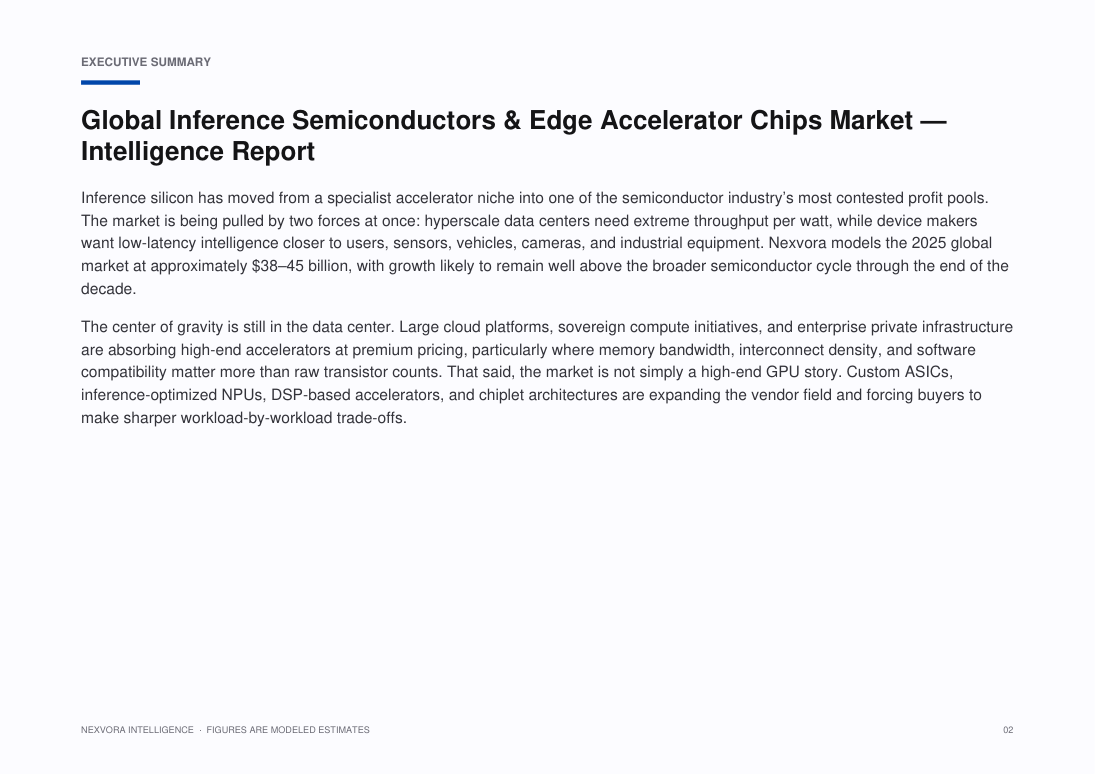
Inference silicon has moved from a specialist accelerator niche into one of the semiconductor industry’s most contested profit pools. The market is being pulled by two forces at once: hyperscale data centers need extreme throughput per watt, while device makers want low-latency intelligence closer to users, sensors, vehicles, cameras, and industrial equipment. Nexvora models the 2025 global market at approximately $•••–••• billion, with growth likely to remain well above the broader semiconductor cycle through the end of the decade.
The center of gravity is still in the data center. Large cloud platforms, sovereign compute initiatives, and enterprise private infrastructure are absorbing high-end accelerators at premium pricing, particularly where memory bandwidth, interconnect density, and software compatibility matter more than raw transistor counts. That said, the market is not simply a high-end GPU story. Custom ASICs, inference-optimized NPUs, DSP-based accelerators, and chiplet architectures are expanding the vendor field and forcing buyers to make sharper workload-by-workload trade-offs.
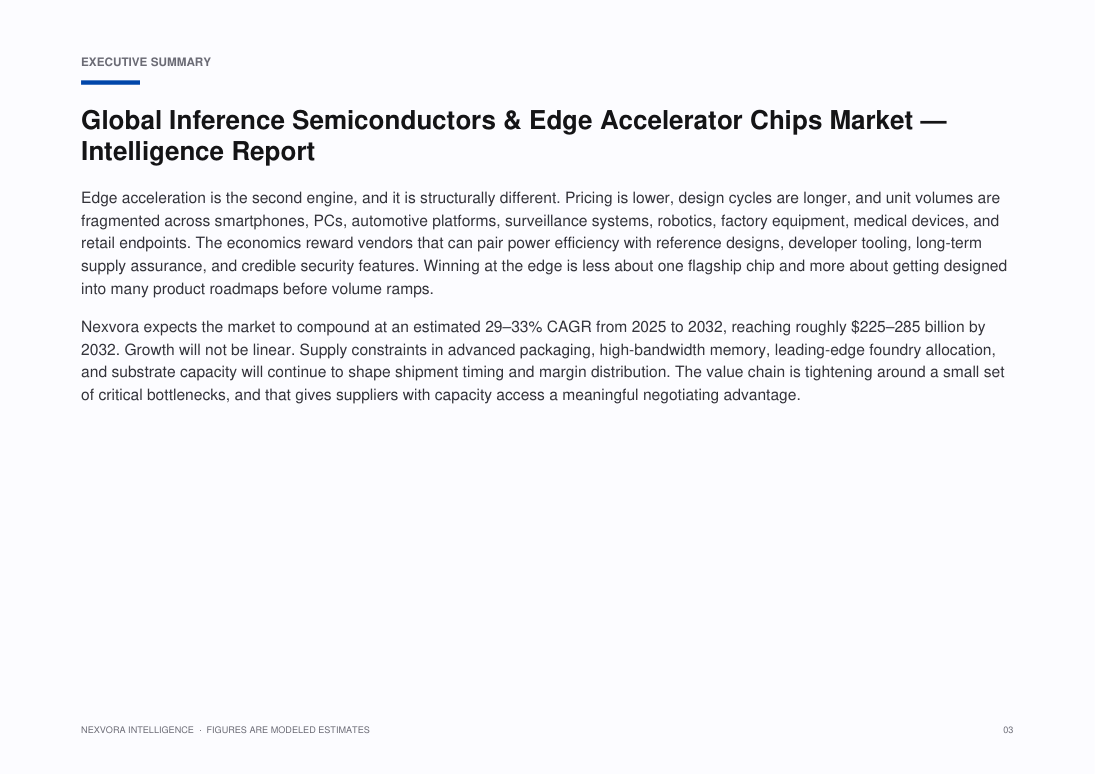
Edge acceleration is the second engine, and it is structurally different. Pricing is lower, design cycles are longer, and unit volumes are fragmented across smartphones, PCs, automotive platforms, surveillance systems, robotics, factory equipment, medical devices, and retail endpoints. The economics reward vendors that can pair power efficiency with reference designs, developer tooling, long-term supply assurance, and credible security features. Winning at the edge is less about one flagship chip and more about getting designed into many product roadmaps before volume ramps.
Nexvora expects the market to compound at an estimated 29–••% CAGR from 2025 to 2032, reaching roughly $•••–••• billion by 2032. Growth will not be linear. Supply constraints in advanced packaging, high-bandwidth memory, leading-edge foundry allocation, and substrate capacity will continue to shape shipment timing and margin distribution. The value chain is tightening around a small set of critical bottlenecks, and that gives suppliers with capacity access a meaningful negotiating advantage.
Specific figures are hidden in this free preview. Unlock the report to see all modeled market sizes, forecasts and growth rates.
What this report covers.
Demand outlook, competitive shifts, and capacity economics across cloud, enterprise, automotive, industrial, and device-edge deployments, 2025–2032
Who this report is for.
- Corporate strategy, planning and M&A teams evaluating the market
- Investors, private equity and venture teams sizing the opportunity
- Product, marketing and go-to-market leaders
- Consultants and analysts building the competitive picture
- Executives planning market entry, expansion or investment
How this report is built.
Nexvora Intelligence developed this market view using a proprietary bottom-up model built around accelerator shipment bands, average selling price ranges, foundry node assumptions, packaging intensity, end-market attach rates, and workload-driven capacity demand.
The analysis separates data-center-class inference accelerators from edge accelerator chips used in client devices, vehicles, cameras, industrial systems, and embedded platforms, then reconciles revenue ranges against supply-chain capacity and buyer procurement patterns.
Forecasts incorporate scenario-weighted assumptions for advanced packaging availability, memory bandwidth requirements, software ecosystem stickiness, cloud capital spending, and edge-device replacement cycles.
All figures in this opening are Nexvora modeled estimates. No external sourced statistics are used in this report opening.
What's inside — a number-free look.
A full outline of the figures and tables you'll get. Specific data, market sizes and forecasts are unlocked with purchase.
List of Figures
- Figure 1: Market Overview and Structure — Inference Semiconductors & Edge Accelerator Chips
- Figure 2: Market Size and Forecast Framework — Inference Semiconductors & Edge Accelerator Chips
- Figure 3: Value Chain and Ecosystem Analysis — Inference Semiconductors & Edge Accelerator Chips
- Figure 4: Market Dynamics — Drivers, Restraints and Opportunities — Inference Semiconductors & Edge Accelerator Chips
- Figure 5: Segment Contribution Analysis — Inference Semiconductors & Edge Accelerator Chips
- Figure 6: Regional Market Landscape — Inference Semiconductors & Edge Accelerator Chips
- Figure 7: Country-level Opportunity Mapping — Inference Semiconductors & Edge Accelerator Chips
- Figure 8: Competitive Positioning Matrix — Inference Semiconductors & Edge Accelerator Chips
- Figure 9: Market Share of Leading Players — Inference Semiconductors & Edge Accelerator Chips
- Figure 10: Adoption and Penetration Trends — Inference Semiconductors & Edge Accelerator Chips
- Figure 11: Technology and Innovation Landscape — Inference Semiconductors & Edge Accelerator Chips
- Figure 12: Pricing and Business Model Analysis — Inference Semiconductors & Edge Accelerator Chips
- Figure 13: Investment, Funding and M&A Landscape — Inference Semiconductors & Edge Accelerator Chips
- Figure 14: Regulatory and Policy Framework — Inference Semiconductors & Edge Accelerator Chips
- Figure 15: Porter's Five Forces Analysis — Inference Semiconductors & Edge Accelerator Chips
- Figure 16: PESTLE Analysis — Inference Semiconductors & Edge Accelerator Chips
- Figure 17: Growth Opportunity Heat Map — Inference Semiconductors & Edge Accelerator Chips
- Figure 18: Future Outlook and Strategic Roadmap — Inference Semiconductors & Edge Accelerator Chips
List of Tables
- Table 1: Market Segmentation Overview — Inference Semiconductors & Edge Accelerator Chips
- Table 2: Segment Definitions and Scope — Inference Semiconductors & Edge Accelerator Chips
- Table 3: Regional and Country Coverage Summary — Inference Semiconductors & Edge Accelerator Chips
- Table 4: Key Company Profiles and Offerings — Inference Semiconductors & Edge Accelerator Chips
- Table 5: Competitive Benchmarking Matrix — Inference Semiconductors & Edge Accelerator Chips
- Table 6: Product and Service Portfolio Mapping — Inference Semiconductors & Edge Accelerator Chips
- Table 7: Market Drivers, Restraints and Trends — Inference Semiconductors & Edge Accelerator Chips
- Table 8: Strategic Initiatives and Developments — Inference Semiconductors & Edge Accelerator Chips
- Table 9: Partnerships and Collaborations — Inference Semiconductors & Edge Accelerator Chips
- Table 10: Research Assumptions and Limitations — Inference Semiconductors & Edge Accelerator Chips
- Table 11: Data Sources and References — Inference Semiconductors & Edge Accelerator Chips
- Table 12: Report Scope and Coverage Summary — Inference Semiconductors & Edge Accelerator Chips
A look at the pages.
107 pages · 20 sections · charts & tables
A genuine peek at the opening pages. Unlock to read every page in full.
6 of 107 pages shown
Turn this market into a plan for your business.
Answer a few quick questions and unlock a personalised operational read — your maturity score, prioritised focus areas and quick wins — mapped to where this market is heading. Result delivered instantly and emailed to you.
- Maturity score & prioritised focus areas
- Practical quick wins and a recommended next step
Questions, answered.
How big is the Global Inference Semiconductors & Edge Accelerator Chips Market?
Nexvora models the Global Inference Semiconductors & Edge Accelerator Chips Market at approximately $38–45B. Full market sizing, segmentation and forecasts are inside the report (modeled estimate).
What is the growth rate (CAGR) of the Global Inference Semiconductors & Edge Accelerator Chips Market?
The Global Inference Semiconductors & Edge Accelerator Chips Market is projected to grow at a CAGR of about 29–33% over the forecast period — a Nexvora modeled estimate detailed across the report's 20 sections.
What does this report include?
A complete market intelligence report — market sizing and forecasts, segmentation, regional and industry analysis, competitive landscape, trends, and strategic recommendations across 20 sections.
How do I access it after purchase?
Instantly, in your secure online viewer. Reports are view-only and available on any device from your library.
Are the figures sourced?
Quantitative figures are Nexvora modeled estimates unless explicitly cited to a referenced source within the report.
Can I buy access for my team?
Yes — add user seats at checkout, or subscribe for bulk access across multiple reports.
Nexvora Intelligence research report. All quantitative figures are modeled estimates — not audited data. Not financial or investment advice.
Generative AI Enterprise Software vs AI Data Center Infrastructure
Choose Microsoft’s generative AI enterprise software if you primarily need **application-level AI capabilities** for business workflows and end-user productivity, and are focused on software rather than underlying hardware. Choose NVIDIA’s AI data center infrastructure portfolio if you need to **build or operate AI computation environments**, with data center GPUs, accelerated systems, networking, and software libraries across on-premises, colocation, cloud, or hybrid deployments. With release timing and software details not publicly disclosed for Microsoft, the right choice ultimately depends on whether your priority is AI-powered enterprise applications (Microsoft) or the foundational compute and infrastructure stack for AI workloads (NVIDIA).
Grounded in published specifications — guidance, not an endorsement.
More market reports
Keep exploring intelligence in this and related sectors.

Global Security Operations Copilots & Autonomous SOC Market — Intelligence Report

India Digital Freight Brokerage Market — Intelligence Report

Global Sovereign Compute Cloud & GPU-as-a-Service Infrastructure Market — Intelligence Report

Global Enterprise Agentic Orchestration & Workflow Automation Market — Intelligence Report
AI Analyst
Insights and answers generated live from Global Inference Semiconductors & Edge Accelerator Chips Market — Intelligence Report's verified data. Modeled estimates — not investment advice.
- The Global AI Inference Semiconductors & Edge Accelerator Chips Market report focuses on demand outlook, competitive dynamics, and capacity economics for inference-focused chips used across cloud, enterprise, automotive, industrial, and device-edge deployments for the 2025–2032 period.
- The report is positioned within the Technology & Software sector, highlighting how AI inference semiconductor and accelerator developments intersect with broader software-driven workloads and deployment models.
- Nexvora Intelligence’s coverage of AI inference semiconductors and edge accelerator chips explicitly spans both centralized cloud inference and distributed edge environments, indicating a holistic view of where inference workloads will be processed between 2025 and 2032.
- Notable: The explicit multi-vertical scope (cloud, enterprise, automotive, industrial, and device-edge) from 2025–2032 suggests that AI inference demand and capacity planning will be structurally important across both traditional IT and embedded/edge systems over the forecast horizon.